



How to Build a Realistic Student Budget for the 2026 Academic Year
Starting university brings a new level of independence, but it also means taking responsibility for expenses that may previously have been handled at home. Rent, groceries, travel, course materials and nights out can quickly add up, particularly when your main source of income arrives only a few times a year.
A realistic budget is not about cutting out everything enjoyable. It is about knowing what you can afford each week so that a generous-looking student finance payment in September does not turn into a financial headache halfway through term.
Start With What You Actually Have Coming In
Before setting spending limits, work out exactly how much money you will have available.
For students normally resident in England, the 2026/27 maximum Maintenance Loan for those living away from home and studying outside London is £10,830. For students studying away from home in London, the maximum is £14,135, while those living with their parents can receive up to £9,118. The amount actually awarded depends largely on household income and individual circumstances. Check the official 2026/27 student finance rates on GOV.UK
Students from Scotland, Wales and Northern Ireland use separate student finance systems, so make sure you are checking the rules for the nation where you normally live rather than simply the university you attend.
If student finance still feels confusing, our guide to funding a UK university degree and understanding student finance covers Maintenance Loans, tuition funding and other sources of financial support in more detail.
Once you know your total income, include any savings, family contributions, scholarships, bursaries and realistic earnings from part-time work.
Turn a Termly Loan Into a Weekly Budget
Maintenance Loans are generally paid into your bank account at the beginning of each term rather than monthly.
That can make your bank balance look healthier than it really is.
Suppose you receive £3,600 at the beginning of a 12-week term. Before treating that as spending money, subtract rent and other unavoidable expenses. If £2,000 is already committed, you actually have £1,600 — around £133 a week — available for everything else.
Setting up separate banking pots for rent, food, travel and discretionary spending can make this much easier. Move money for essential costs aside as soon as your funding arrives rather than relying on yourself not to spend it.
The UCAS student budgeting guidance also includes a budget calculator that can help you estimate living costs before starting university.
Separate Essential Costs From Lifestyle Spending
Your budget becomes easier to manage when expenses are divided into two categories.
Fixed or essential costs might include:
- Rent
- Gas, electricity and water if not included
- Broadband
- Mobile phone
- Transport
- Insurance
- Essential course materials and software
Your variable spending covers things such as groceries, takeaways, nights out, clothes, subscriptions and entertainment.
Accommodation will usually be the largest expense. Before signing for private student housing, check carefully whether advertised rent includes utility bills. A property that initially looks cheaper can become considerably more expensive once energy, water and broadband are added.
Students preparing to move away from home can also use our guide to what to pack for your first term at a UK university to avoid buying things unnecessarily after arriving.
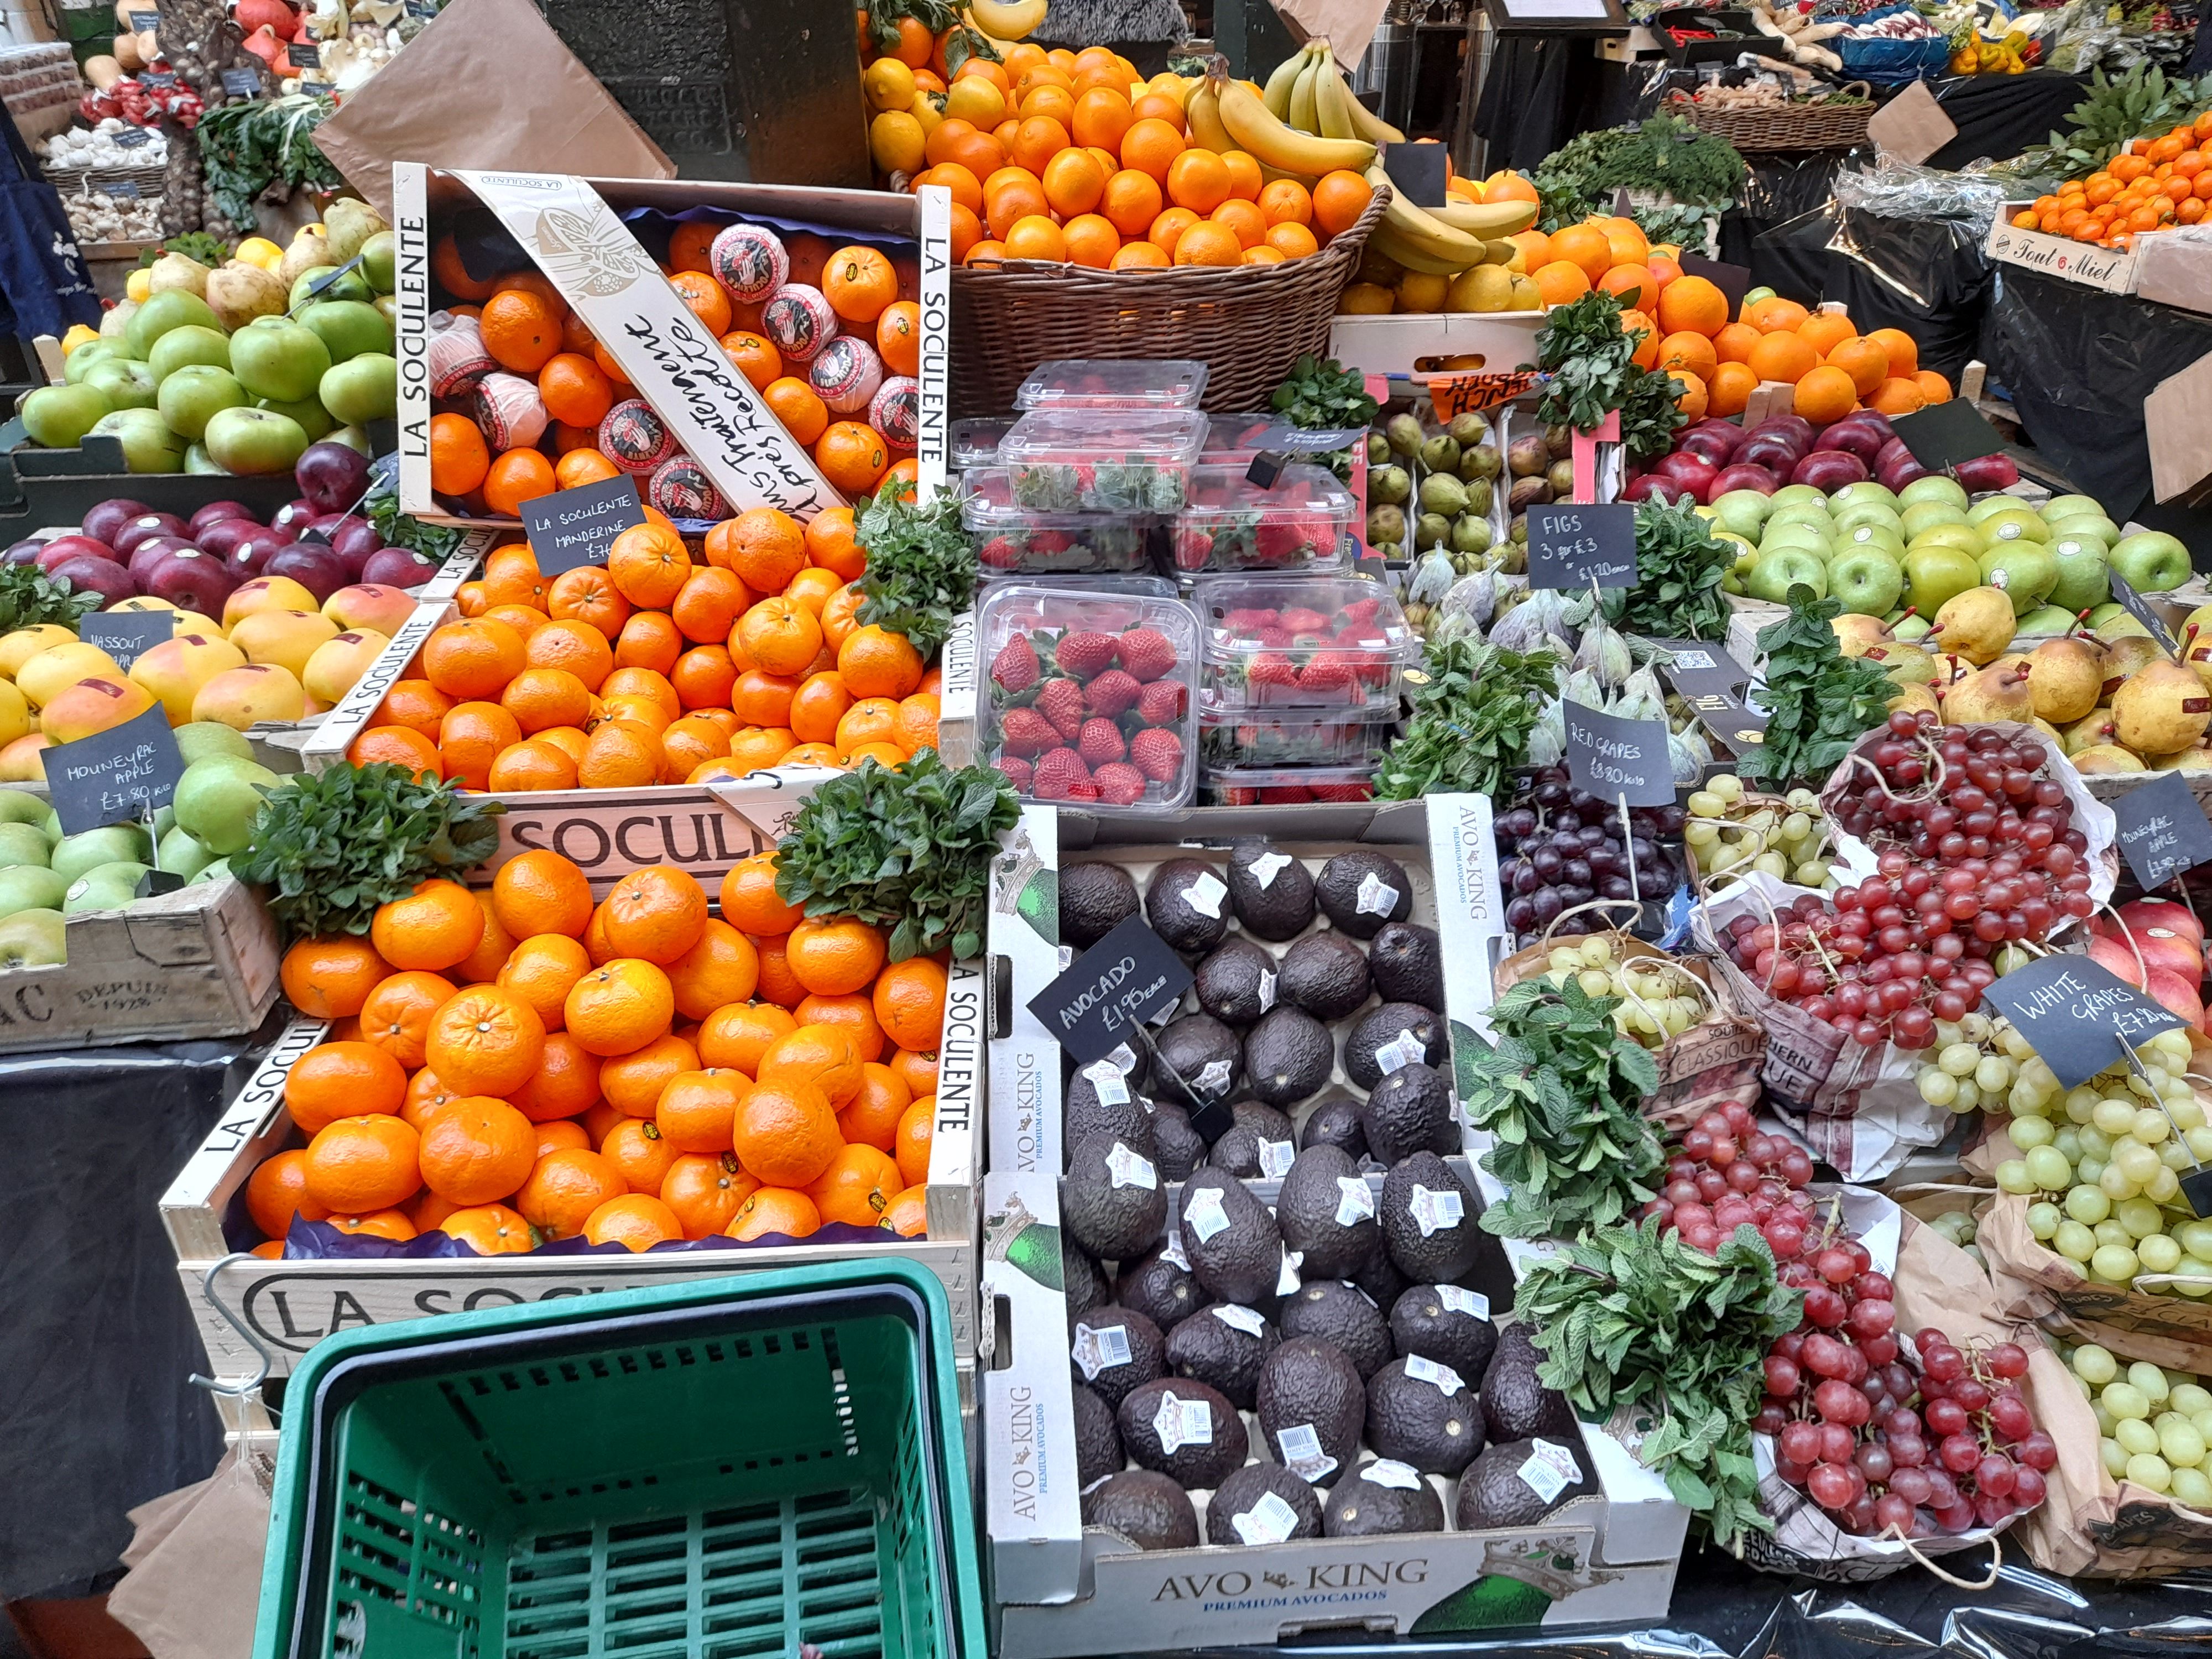
Give Yourself a Realistic Food Budget
Food is one of the easiest areas for spending to drift upwards.
Buying lunch on campus several times a week, using delivery apps and making frequent convenience-store trips can consume a surprisingly large portion of your weekly allowance.
Meal planning does not have to mean living on the same inexpensive meal every night. Decide on several meals before shopping, check what you already have and make a list.
Cooking with housemates can also make larger packs of ingredients more economical, provided everyone contributes fairly.
Student discounts and supermarket loyalty schemes can help, but a discount is only a saving if you were going to buy the item anyway.
Budget for Having a Social Life
A student budget that assumes you will never go out, buy a coffee or travel home is unlikely to survive for very long.
Build social spending into the plan.
If you can afford £30 or £40 for entertainment in a particular week, knowing that limit beforehand is much more useful than spending freely and worrying about the balance afterwards.
Some weeks will naturally cost more than others. Freshers' Week, birthdays and society events may require a larger allowance, while quieter weeks give you an opportunity to spend less.
Build a Small Emergency Fund
Unexpected costs are almost inevitable during university.
A broken laptop, emergency train ticket home or unexpectedly expensive course material can easily disrupt an otherwise sensible budget.
Even putting aside £5–£10 a week can gradually create a useful buffer. Keep it separate from everyday spending so that it remains available for genuine unexpected expenses.
If your budget leaves no room whatsoever for emergencies, speak to your university. Many institutions provide hardship funds, bursaries and dedicated student money advisers.
Be Careful With Student Overdrafts
Interest-free student overdrafts can be useful, but they are still borrowed money.
MoneyHelper's guidance on student bank accounts explains that many student accounts offer interest-free overdraft facilities while studying, but the money ultimately has to be repaid.
Try to treat an overdraft as a buffer rather than part of your regular income. The danger comes when everyday spending depends on being permanently overdrawn.
Credit cards require even greater caution because interest can become expensive if balances are not repaid in full.
Check Your Budget Every Week
Your first university budget will not be perfect.
After a few weeks, you may discover that you spend less on transport than expected but considerably more on food. Adjust accordingly rather than abandoning the budget altogether.
Mobile banking makes this much easier. Check transactions regularly, set balance alerts and review subscriptions you no longer use.
Money worries can also affect wider wellbeing. If financial pressure is beginning to feel overwhelming, speaking to your university's student support service is preferable to ignoring it. Simple habits for managing stress, including reflective techniques such as journalling and structured self-reflection, can also help you recognise when worries are beginning to build.
Make Your Money Work for the Whole Term
Learning to manage money is one of the less obvious skills university teaches you.
Work out what is coming in, protect the money needed for essentials, give yourself a weekly allowance and leave some room for enjoying university life.
Most importantly, do not wait until your account is almost empty before checking where your money has gone. A ten-minute budget review each week can make the difference between reaching the end of term comfortably and spending December wondering how September's maintenance payment disappeared.